
Yes, buy now pay later works for car parts at plenty of U.S. retailers, both online and in-store. You’ll typically see two provider types at checkout: pay-in-4 specialists that split your total into four interest-free payments, and longer-term lenders that finance bigger jobs over months. Look for the BNPL logo at checkout, or open the provider’s app to generate a virtual card before you shop.
TL;DR:
- Pay-in-4 plans are interest-free only if payments are made on time, whereas longer-term financing can include interest and impact credit scores with hard checks.
- Returns usually require merchant processing before BNPL adjustments, and delays in refunds can cause temporary active balances on your account.
- Using multiple BNPL plans simultaneously can lead to significant monthly obligations; managing two or three active plans is advisable.
- Most BNPL providers perform real-time eligibility checks, which take seconds and depend on purchase size, payment history, and merchant risk profile.
- Confirm part compatibility and read all provider terms carefully before financing to avoid surprises or payment issues.
Table of Contents
- Which BNPL Providers Work for Car Parts?
- How Does BNPL Work at Checkout for Auto Parts?
- What Does BNPL Cost, and Does It Affect Your Credit?
- What Happens When You Return a BNPL-Financed Part?
- Staying Safe: Terms, Fees, and Juggling Multiple Plans
- The BNPL Timeline: From Selection to Final Payment
- Why We Built Financing Into the Buying Experience
- Ready to Finance Your Wheel Light Express Order?
- Where to Verify BNPL Terms and Protections
- Sources
Which BNPL Providers Work for Car Parts?
Not every provider fits every purchase. A $60 headlight harness and a $1,200 suspension kit call for different repayment structures, and the six major players split cleanly into two camps.
- Affirm leans toward longer financing terms, sometimes offering 0% promotional offers depending on the merchant, and tends to suit bigger-ticket parts orders rather than a $40 accessory.
- Klarna offers both pay-in-4 and extended plans, and it’s widely integrated at checkout with parts retailers, including carparts.com’s Klarna partnership.
- Sezzle focuses on pay-in-4 and gives shoppers a virtual-card option, which matters because many merchants support multiple BNPL providers, and a virtual card lets you use Sezzle even where it’s not directly built into checkout.
- PayPal Pay Later rides inside your existing PayPal checkout button, with multiple plan lengths depending on order size, and PayPal frames this as a way to get parts immediately without the interest rates that often come with a credit card, as long as you pay on time.
- Zip runs pay-in-4 and split-pay structures across a wide merchant network.
- Sunbit shows up less online and more at physical counters. It’s built for vehicle repair and point-of-service financing, and dealer data shows high approval rates in some dealership contexts where Sunbit is offered at the service desk.
How Does BNPL Work at Checkout for Auto Parts?
The mechanics are nearly identical across providers, whether you’re buying brake pads online or financing rock lights for a truck build.
- Add your parts to the cart and select a BNPL provider at checkout, or open the provider’s app first to generate a virtual card if the retailer doesn’t have a direct integration.
- The provider runs a real-time eligibility check. This isn’t a loan committee review. It’s an automated decision that typically returns in seconds, based on your purchase size, payment history, and the merchant’s risk profile.
- The provider pays the merchant in full, and you walk away with your order while repaying the provider on the schedule you picked, whether that’s four payments or a multi-month plan.
Some providers issue a single-use virtual card you paste directly into a normal card field, which works even at retailers with no formal BNPL button. Others integrate at the point of sale for in-store repairs and installations.
Pro Tip: Have your ID, billing address, and a backup payment method ready before you start checkout. Eligibility checks move fast, but a mismatched billing address is the most common reason an instant approval stalls.
What Does BNPL Cost, and Does It Affect Your Credit?
Cost and credit impact are the two things buyers skip reading, and the two things that bite them later.
Pay-in-4 plans are usually interest-free, but only if every payment lands on time. Longer-term plans, the kind Affirm often uses for bigger purchases, can carry a real APR, so read the total cost of the loan before you click “confirm,” not just the monthly number.
- Pay-in-4 typically uses a soft credit check that doesn’t touch your score.
- Longer-term financing may involve a hard credit check, depending on the provider and loan size, so confirm the provider’s policy before applying.
- Missing a payment can trigger late fees and may affect your ability to get approved for future BNPL purchases.
Approval decisions on most pay-in-4 applications land within seconds, but being approved once doesn’t guarantee approval on your next purchase — the underlying algorithm reweighs your recent payment history and the new purchase amount every time.
Financial writers are blunt about the real risk here: BNPL is only interest-free when you pay on schedule, and stacking several active plans across different providers can quietly add up to a real monthly obligation. One $80 pay-in-4 plan feels harmless. Four of them running at once is a second car payment.
What Happens When You Return a BNPL-Financed Part?
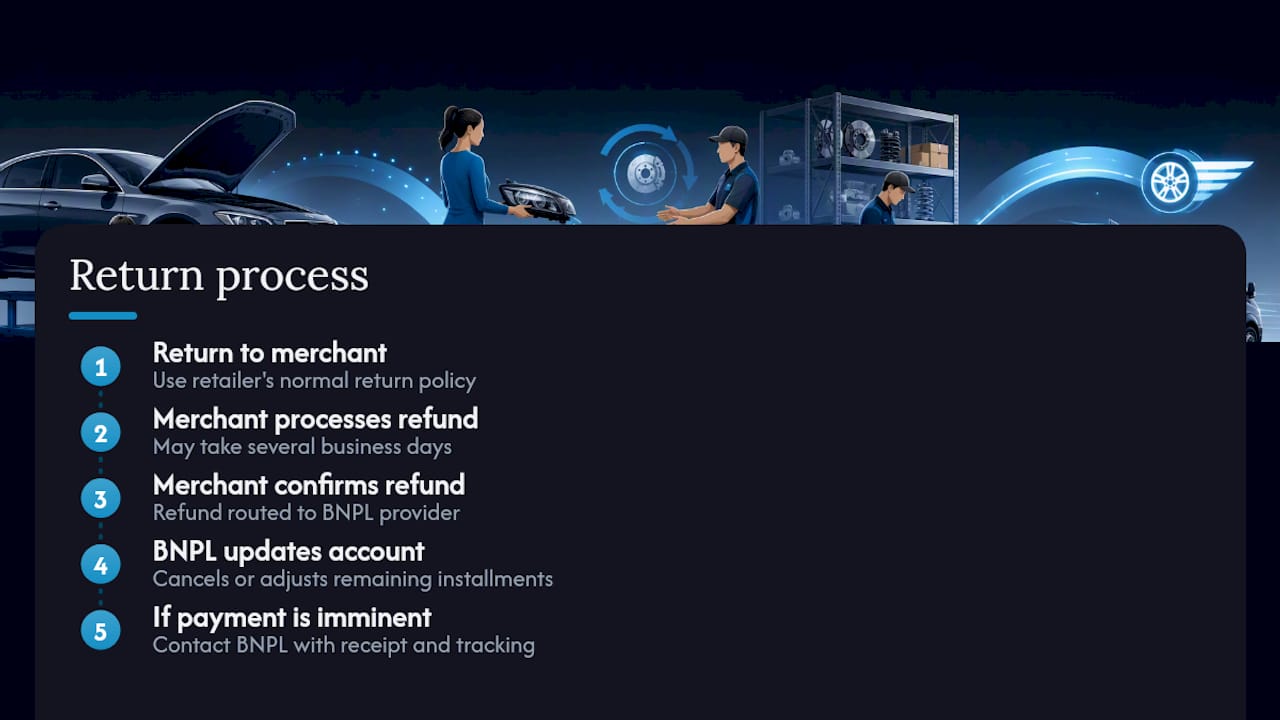
Returns work through the merchant first, not the BNPL provider. If a wheel light kit doesn’t fit or a harness arrives damaged, you return it to the retailer under their normal policy. Once the merchant processes and confirms that refund, the BNPL provider adjusts or cancels your remaining installments to match what you actually kept.
The timing gap is where most confusion happens. A merchant might take several business days to process a return, and during that window your BNPL account can still show an active balance and an upcoming payment date. That’s normal, not a sign something went wrong, but it’s worth watching.
If a refund seems slow, keeping your merchant return receipt and confirmation email speeds up reconciliation with the BNPL provider considerably. Don’t rely on memory. Screenshot the return confirmation the day you ship the part back, and note the tracking number.
If a payment is scheduled to draft before your refund posts, contact the BNPL provider directly rather than assuming the merchant will handle it. Providers can usually pause or adjust an installment once you show proof the return is in motion, but they need to hear about it first.
Staying Safe: Terms, Fees, and Juggling Multiple Plans
Read the plan terms before you tap “approve,” not after. The screen showing your four payment dates also shows the late fee structure, and that’s the part most people skip.
A few habits keep BNPL working for you instead of against you:
- Check whether your plan is pay-in-4 (usually interest-free on time) or a longer loan (usually carrying APR) before you commit.
- Set a calendar reminder for each installment date rather than trusting autopay alone.
- Avoid opening a new BNPL plan for every purchase across every provider. Two or three active plans at once is manageable. Six is a spreadsheet problem.
- Confirm part compatibility with your vehicle before financing it. A financed part you can’t use is still a payment obligation.
Late fees on a missed pay-in-4 installment are usually smaller than a missed longer-term payment, but a pattern of late payments on either type can affect future approvals across providers, not just the one you missed with.
The BNPL Timeline: From Selection to Final Payment
A typical car-parts BNPL purchase runs on a predictable clock, whether you’re buying rock lights or a replacement wiring harness.
Day 0: You select the part, choose a BNPL provider at checkout, and get an eligibility decision in seconds. The provider pays the merchant in full immediately.
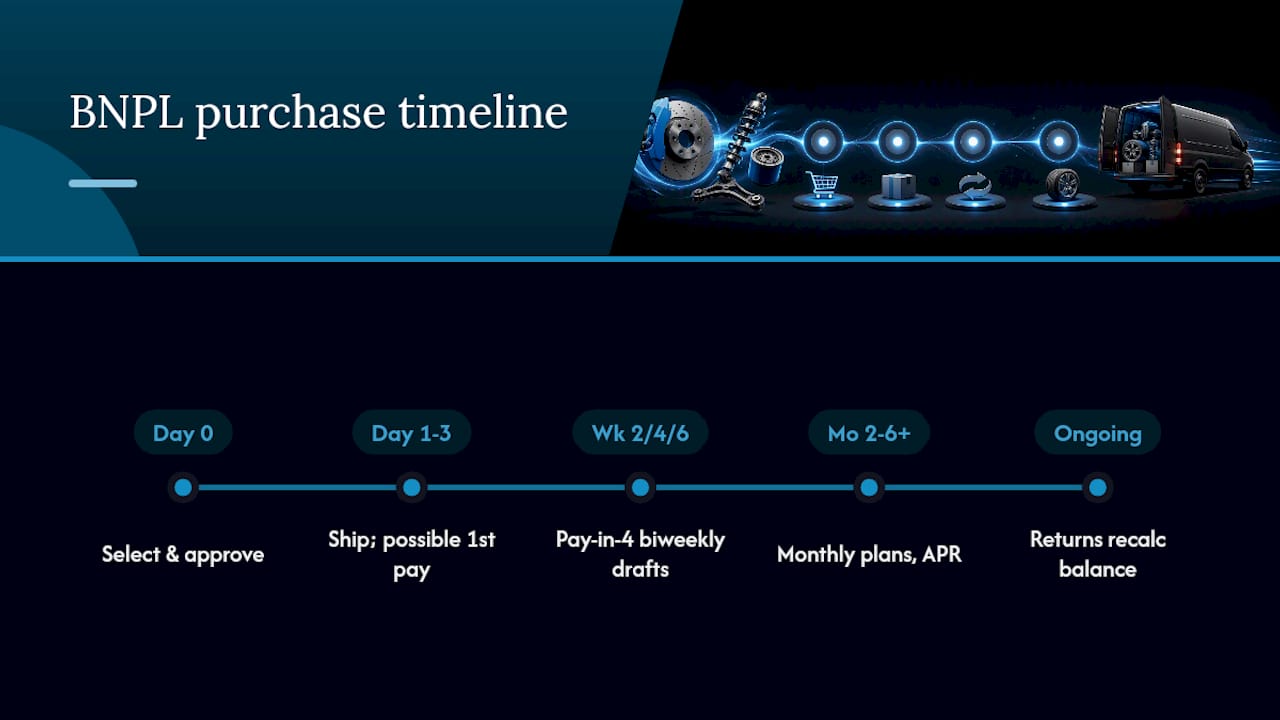
Days 1 to 3: The merchant ships your order. Your first installment, if the plan requires an upfront payment, is often charged the same day you check out.
Weeks 2, 4, and 6 (pay-in-4): Remaining installments draft automatically from your chosen payment method, roughly every two weeks, until the balance is clear.
Months 2 through 6+ (longer-term plans): Monthly payments continue on the schedule set at approval, with interest accruing if the plan carries an APR.
Ongoing: If you return a part anywhere in this window, the merchant refund triggers the provider to recalculate your remaining balance, which can mean fewer future installments or a partial refund credited to your original payment method.
Knowing this rhythm ahead of time makes it far easier to plan around payday, avoid overlapping plans, and budget for a bigger lighting upgrade without surprises.
Why We Built Financing Into the Buying Experience
We design every kit in Louisiana because we’d rather control quality than chase the cheapest overseas supplier, and financing exists so that decision doesn’t put good lighting out of reach. Before you finance anything: confirm the kit fits your specific vehicle and lighting setup, read your BNPL provider’s terms in full, and keep every receipt until your plan is paid off.
— Christopher
Ready to Finance Your Wheel Light Express Order?
You’ve seen how pay-in-4 and longer-term plans work elsewhere. Financing is available for lighting kits designed and assembled in the U.S., not sourced from an overseas catalog; for more on related products, see our EV charging accessories collection.
Start with our wheel light ring and strip kits if you’re building out a full setup, or check the replacement wire harness page if you’re repairing an existing install. Financing shows up right at checkout, the same real-time approval flow covered above. Before you commit to a plan, read your provider’s terms closely, and reach out to our support team if you’re unsure whether a kit fits your vehicle. Compatibility questions are free; a returned kit financed on a plan is a hassle we’d rather help you avoid.
Where to Verify BNPL Terms and Protections
Before financing any purchase, check the provider’s own terms page for exact fees and APR ranges. The FDIC’s deposit insurance resources and a provider’s Better Business Bureau profile are both solid starting points for confirming legitimacy and reading real complaint histories before you commit to a plan.
Sources
- Buy Now Pay Later for auto parts | Sezzle
- PayPal buy now pay later for automotive
- FDIC — Deposit Insurance resources